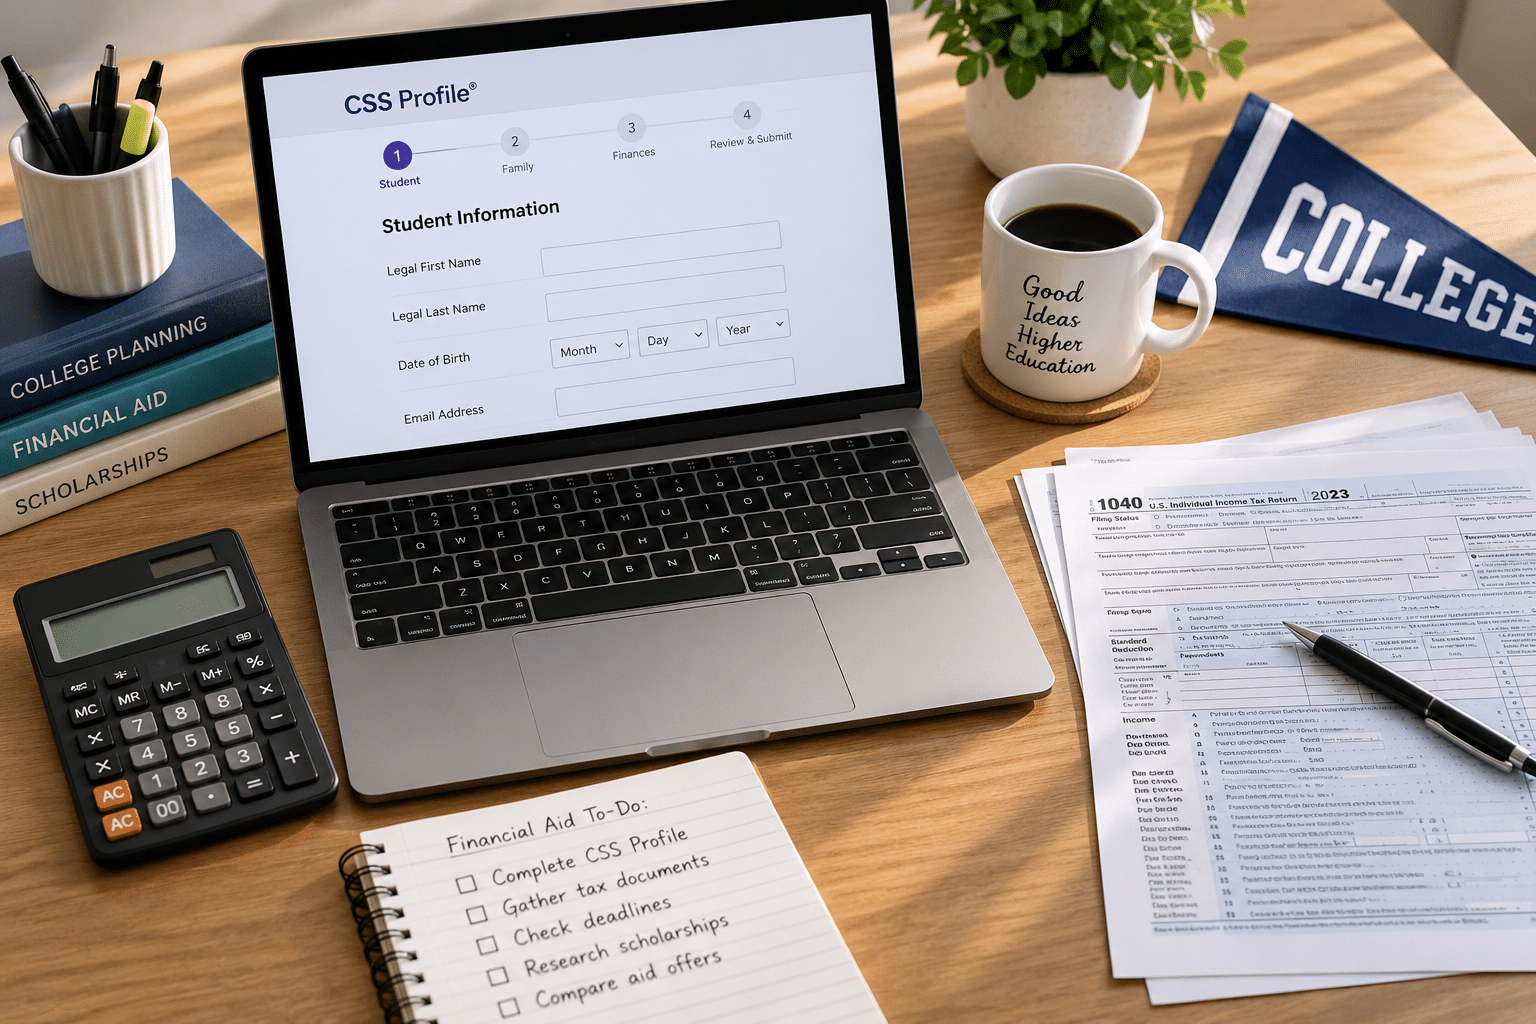
The best CSS Profile help starts with timing and accuracy. First, begin at least two weeks before your earliest college priority date. Next, select the correct aid year and enter the student’s name, birth date, and Social Security number exactly as they appear on legal documents. In addition, answer every student question about the student, not the parent. Finally, watch your dashboard and email for IDOC document requests after you submit.
If you want help with the CSS Profile from a local team, College Planning Source can guide you. The San Diego firm was founded in 2005 by Michelle Mai, and its College Funding and Financial Aid Forms services include CSS Profile registration and submission. Families can start with a complimentary one-on-one college planning assessment or a free live webinar on admissions and financial aid. Visit collegeplanningsource.com to see current programs and book an assessment.
Quick Takeaways
- The 2027-2028 CSS Profile opened October 1, 2026, and it uses your 2025 federal tax return.
- There is no single deadline. Each college sets its own, and early decision dates often fall in November.
- The form costs $25 for the first school and $16 for each additional one. However, families with adjusted gross income up to $100,000 typically qualify for a fee waiver.
- College Board allows only one correction per academic year, so accuracy matters more than speed.
- Mismatched student details between two parent applications are a common cause of delays.
- College Planning Source offers CSS Profile help through its financial aid forms services.
What Is the CSS Profile and Who Needs It?
The CSS Profile is College Board’s online financial aid application. A few hundred colleges, universities, and scholarship programs use it to award their own grants and scholarships outside the federal aid system. You only need it if a school or scholarship on your list requires it. College Board’s participating institutions list will confirm that.
However, the Profile does not replace the FAFSA. The FAFSA covers federal aid such as Pell Grants and federal loans. The Profile, by contrast, gives private colleges and some selective public universities a fuller picture of family finances. For example, it asks about home equity, small-business details, current-year income estimates, and often noncustodial parent finances.
The stakes are real. College Board reports that the Profile unlocks more than $10 billion in nonfederal aid each year.
When Is the 2027-2028 Deadline?
There is no single deadline. Instead, submit before the earliest priority date among your schools and start at least two weeks early, as the College Board recommends. For the 2027-2028 school year, the form opened October 1, 2026. Early decision and early action deadlines often fall in November. Regular decision deadlines usually land between January and March.
In addition, the National College Attainment Network suggests a personal deadline five days ahead of the real one. That buffer covers a missing tax figure or a parent who needs one more weekend.
| Application plan | Typical timing | What to do now |
|---|---|---|
| Early decision or early action | Often due in November | Start now and gather your 2025 tax return this week |
| Regular decision | Usually January to March | Finish by December to leave room for IDOC requests |
Which Documents Should You Gather First?
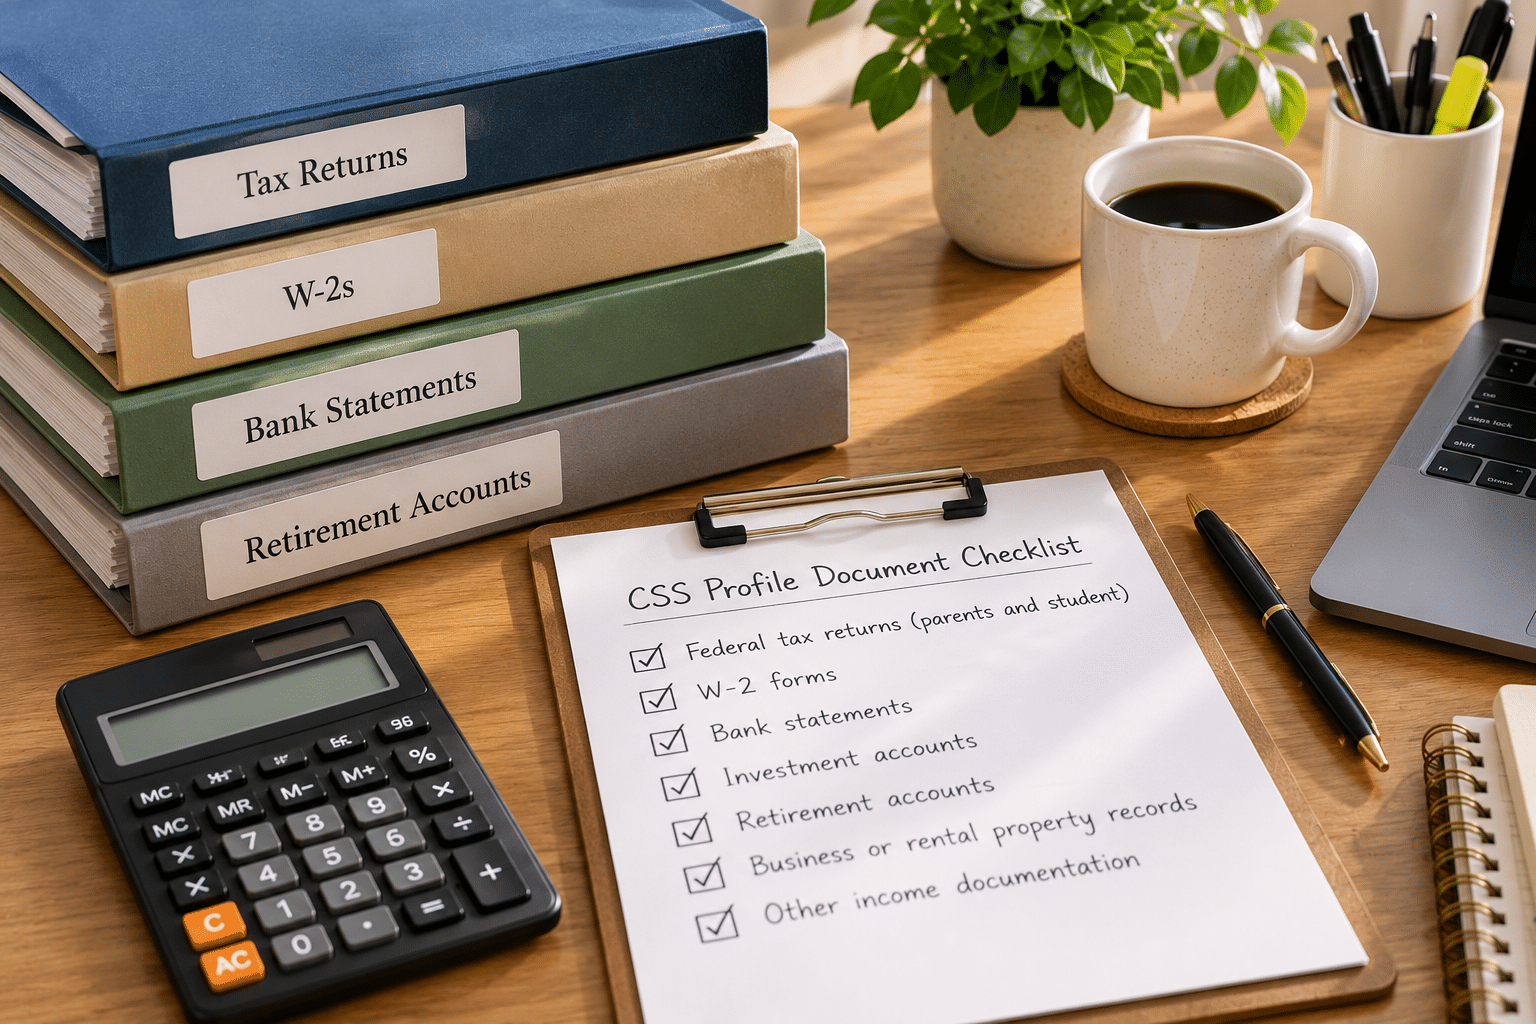
Before you start, gather your 2025 federal tax returns, W-2s and 1099s, bank and investment statements, retirement account values, your home’s estimated value and mortgage balance, and any business or farm records. With everything in one folder, most families finish in 45 minutes to two hours. That is the range the College Board estimates.
Document checklist
- 2025 federal tax returns for parents and student, including all schedules
- 2025 W-2s and 1099s for every working household member
- Estimates of 2026 income, since the form asks for current year figures too
- Bank, brokerage, and retirement account balances as of the day you file
- Home value estimate, purchase year, and remaining mortgage balance
- Business or farm tax returns and balance information, if they apply
- 529 plan and other education savings balances
- The College Board account the student used for the SAT, PSAT or AP exams
That last item matters more than it seems. The SAT-based fee waiver only applies when the student logs in with the same College Board account used for the SAT.
What Mistakes Cause the Most Delays?
The most common errors are choosing the wrong aid year, mistyping the student’s name, birth date, or Social Security number, and parents answering student questions about themselves. Families also report parent assets in the student section or accidentally select a graduate program. As a result, processing slows down, or the college calculates the wrong financial need.
| Mistake | What it causes | How to avoid it |
|---|---|---|
| Choosing the current school year | The college receives the wrong aid year | Seniors applying now should select 2027-2028 |
| Typos in the student’s name, birth date or SSN | Parent and student records fail to link | Copy details from a Social Security card or passport |
| Parents answering student status questions about themselves | Incorrect dependency answers | Check whether each question is about the student or the parent |
| Parent assets entered in the student section | Inflated student contribution and lower aid | Double-check every asset question |
| Selecting a law, medical, or business graduate school | The form goes to the wrong program | Seniors should only select undergraduate colleges |
| Skipping the special circumstances section | Lost context about job loss or medical bills | Briefly explain any major financial change |
The special circumstances section deserves extra attention. After all, financial aid officers can only consider what they can see. A recent layoff, high medical costs, or support for an elderly relative all belong there. This is also where a second reviewer offering CSS Profile help often catches what a family missed.
How Do Divorced or Separated Parents File?
When parents are divorced, separated, or never married, many colleges require a separate application from the noncustodial parent. That parent creates their own College Board account and completes their own form. Both applications must list the same student name, date of birth, and answer for which parent the student lives with. Otherwise, the records may not process correctly.
A surprisingly common error is when both parents say the student lives with them, or neither parent does. Stepparent information may also be required. If contact with the noncustodial parent is impossible or unsafe, many colleges accept a waiver request. Each school decides individually, though, so start that conversation early.
How Much Does It Cost, and Who Qualifies for a Fee Waiver?
Sending the Profile to your first college costs $25, and each additional college costs $16. However, domestic first-year undergraduates file for free if their family adjusted gross income is up to $100,000, if the student received an SAT fee waiver, or if the student is an orphan or ward of the court under age 24. Waivers cover all application and reporting fees.
College Board checks eligibility automatically while you complete the form. Noncustodial parents with family adjusted gross income up to $100,000 also file for free. For families above that line, eight colleges cost $137. So before you pay, confirm which schools on your list truly require the form.
What Happens After You Submit?
Once you submit, College Board sends your application to each college you selected. Some colleges then request supporting documents through IDOC, College Board’s Institutional Documentation Service. IDOC collects tax returns, W-2s, and school-specific forms. If IDOC applies, you’ll get a notice in your College Board account and by email, and the service is free.
Many delays start right here. Families submit the form, celebrate, and then miss the IDOC request. To avoid that, keep your figures consistent with the documents you upload, sign every signature line and check your dashboard weekly. Keep in mind that some colleges skip IDOC and use their own portals instead.
Can You Fix an Error After Submitting?
Yes, but only once. Use the Correct Your CSS Profile option on your College Board dashboard. College Board allows one correction per academic year. If you have already used it and find another error, you must contact each affected college’s financial aid office directly.
For that reason, review everything one more time before you pay and submit. Compare each income figure against your 2025 tax return and confirm every school code.
When Does Professional CSS Profile Help Make Sense?
Professional CSS Profile help makes the most sense for families with divorced or separated parents, a family business, rental property, significant assets, several children in college or a tight early decision deadline. On the other hand, families with one W-2 income and simple finances can often file alone using College Board’s free tutorials.
| Your situation | Recommended approach |
|---|---|
| Simple finances, one or two schools that require the form | College Board’s free tutorials are usually enough |
| Divorced, separated, or never married parents | Get guidance before either parent starts |
| Self-employed or business owner parents | Have a professional review income and asset reporting |
| Early decision deadline in November | Start now and get a second set of eyes before submitting |
| A big change in income since 2025 | Get advice on the special circumstances section |
Why Families Choose College Planning Source
Michelle Mai founded College Planning Source in 2005. During a work-study job in the UC Santa Barbara financial aid office, she saw how many families struggled with the aid system. Today, the firm’s CSS Profile help sits inside a broader financial aid forms service that also covers FAFSA submission, institutional aid forms, financial aid negotiation letters, and ongoing support.
Beyond the forms, the team helps with the planning behind them. This includes cost-of-attendance outlines, need-based and merit aid estimates, and a financially balanced college list. The office is at 10875 Rancho Bernardo Road in San Diego, and virtual counseling sessions are available too.
Frequently Asked Questions
Is the CSS Profile the same as the FAFSA?
No. The FAFSA is the federal government’s free application for grants, work-study, and federal student loans. The CSS Profile, on the other hand, is run by College Board and used by a few hundred colleges and scholarship programs to award their own aid. Many selective private colleges require both, so check each school’s financial aid page.
Does the form ask about home equity?
Yes. Unlike the FAFSA, it asks for your home’s estimated value, purchase year, and remaining mortgage balance. Each college decides how heavily to weigh home equity, so the same answers can lead to different results at different schools. Estimate honestly and keep a note of how you reached the figure.
Do you need to file every year?
Yes, if your college requires it and you want to keep receiving need-based institutional aid. Students refile each year of college, just like the FAFSA. Requirements for returning students vary, however, so watch your student portal and financial aid emails each fall.
Can you add colleges after submitting?
Yes. You can add schools from your College Board dashboard after you submit, which helps once early round decisions come in. Each added school carries the standard $16 reporting fee. That fee does not apply if your family qualifies for a fee waiver, since waivers cover all application and reporting fees.
Get Expert Help Before Your Deadline
The 2027-2028 form is open now, and November deadlines are close. If your family has divorced parents, business income, or several students in college, College Planning Source can take the guesswork out of the process. The team can help you register, complete, and submit the form, then follow through on the FAFSA, institutional forms, and aid negotiations. Start with a complimentary one-on-one college planning assessment. Call 858.676.0700 or visit collegeplanningsource.com to book.
At College Planning Source, we help students and families navigate every step of the college admissions process. Get direct one-on-one guidance with a complimentary virtual college planning assessment—call 858-676-0700 or schedule online at collegeplanningsource.com/assessments.