A student financial planner helps you budget for college by estimating what each school will actually cost your family, finding ways to lower that number through financial aid and scholarships, and building a payment plan from savings, income and responsible borrowing. Instead of reacting to a bill after admission, families know their target budget before applying and choose schools that fit it.
For families in San Diego and across Southern California, College Planning Source offers this kind of guidance alongside admissions planning. Founder Michelle Mai worked in the financial aid office while attending UC Santa Barbara, and the Rancho Bernardo firm has helped families plan for both admissions and college funding since 2005. Every family can start with a complimentary one-hour virtual college planning assessment that reviews the student’s goals and the family’s funding plan.
Quick Takeaways
- A student financial planner focuses on the full cost of attendance, not just tuition, and compares what each college will likely cost your family after aid.
- Published prices are misleading. In 2026 to 2027, the average in-state public four-year sticker price is $12,290, but the average net tuition after grants is about $1,920, according to the College Board.
- About 70 percent of full-time undergraduates receive grant aid, so filing the FAFSA or CADAA on time matters for almost every family.
- California students should file by March 2, 2027 to be considered for a Cal Grant for the 2027 to 2028 school year.
- College Planning Source offers a free one-hour virtual assessment and a college funding program designed for parents.
What Does a Student Financial Planner Do?
A student financial planner helps families plan, pay for and manage the cost of college. The work usually includes estimating the cost of attendance at each school, explaining how financial aid formulas treat your income and assets, identifying scholarships, coordinating savings such as 529 plans, and building a year by year budget so the student graduates with manageable debt or none at all.
The title varies, from college funding advisor to college planning specialist, but scope matters more than the label. Some advisors only fill out aid forms, while others connect college costs to the family’s cash flow, taxes, retirement savings and younger siblings’ future tuition.
What Expenses Should a College Budget Include?
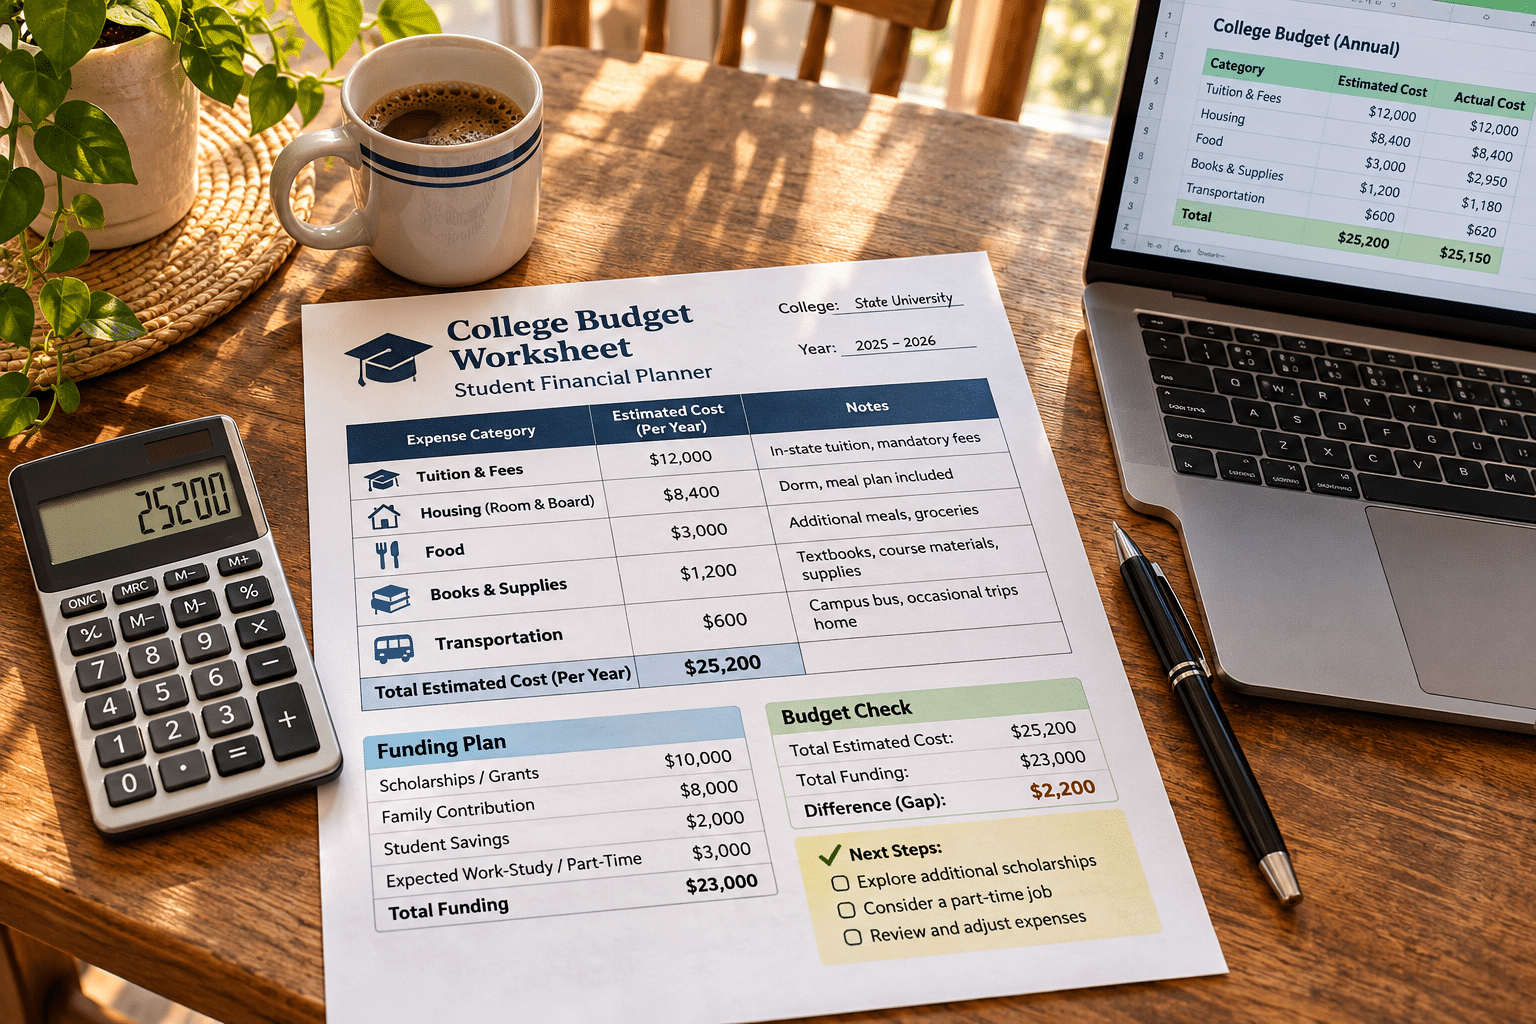
A complete college budget should include tuition and fees, housing, food, books and supplies, transportation and personal expenses. Colleges publish all of these together as the cost of attendance. Families who budget only for tuition often underestimate the real annual cost by many thousands of dollars, especially when a student lives on campus or far from home.
Here is how the main categories break down:
| Expense Category | What It Covers | Budgeting Tip |
|---|---|---|
| Tuition and fees | Instruction, campus services, mandatory fees | Check whether the rate is fixed or can rise each year |
| Housing | Residence hall or off-campus rent | Compare campus housing with nearby rentals and roommate options |
| Food | Meal plans or groceries | Choose the smallest meal plan the student will actually use |
| Books and supplies | Textbooks, course materials, a reliable laptop | Rent or buy used books when allowed |
| Transportation | Flights, gas, parking permits, transit passes | Plan for trips home during holidays and breaks |
| Personal expenses | Phone, clothing, health costs, entertainment | Set a monthly spending allowance with the student |
How Much Does College Cost in 2026 to 2027?
According to the College Board’s Trends in College Pricing and Student Aid 2026 report, average published tuition and fees for 2026 to 2027 are $12,290 for in-state students at public four-year universities, $32,730 for out-of-state students at those same schools and $46,350 at private nonprofit four-year colleges. Housing, food and other expenses come on top of these amounts.
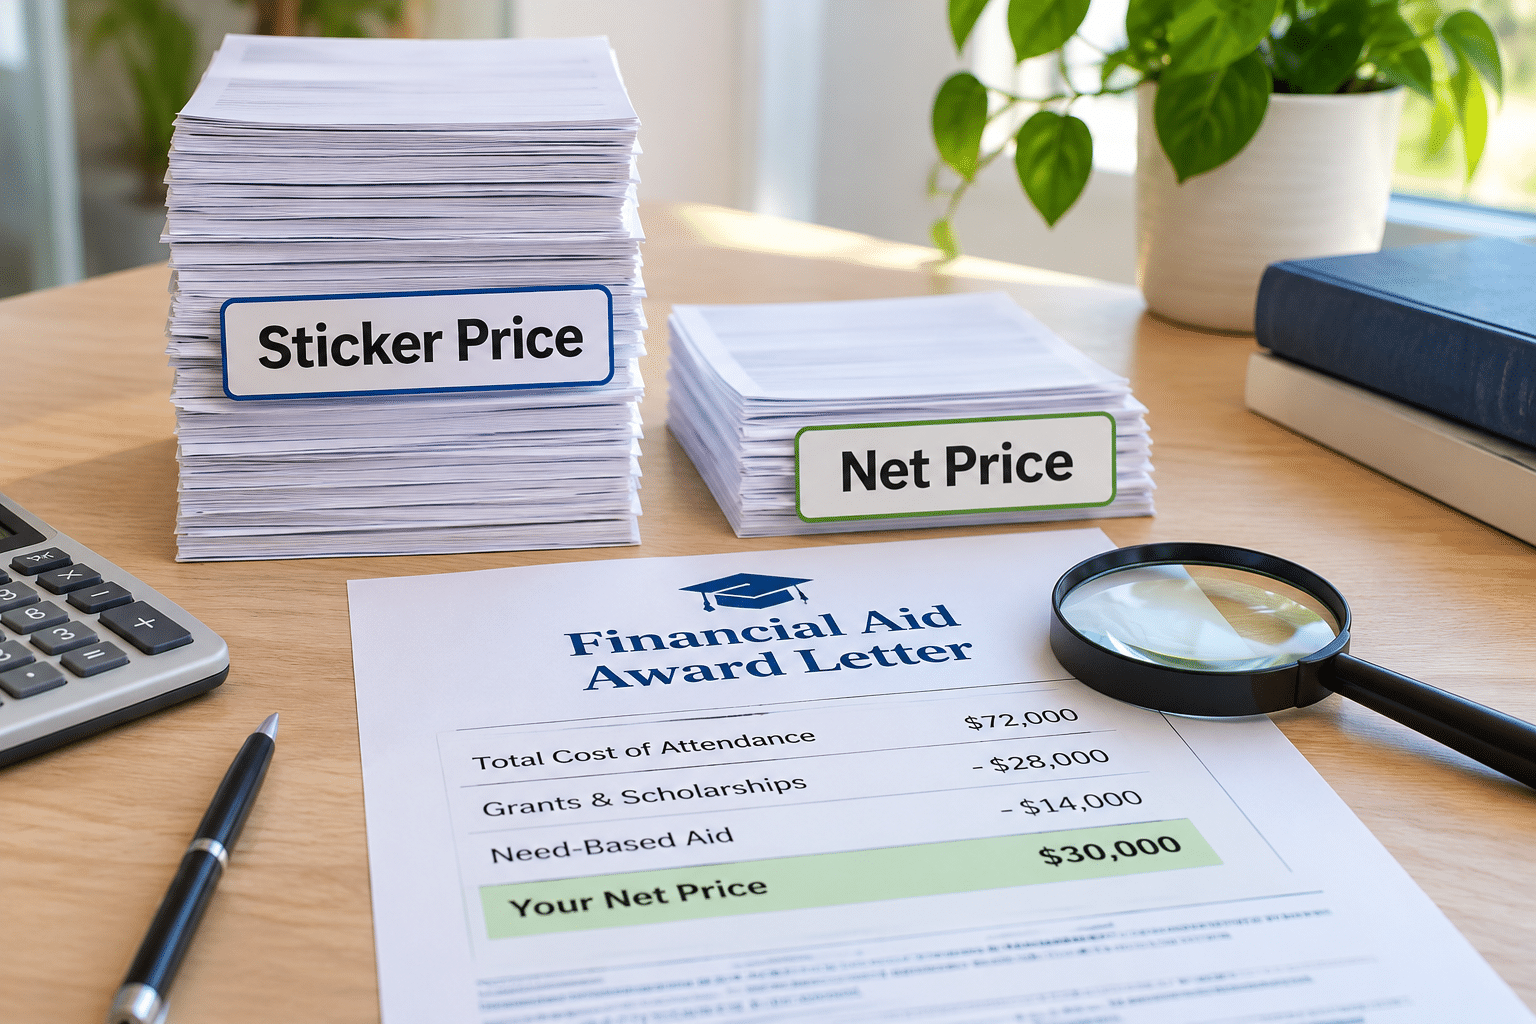
The more useful number is net price, which is what families pay after grants and scholarships. The College Board estimates that first-time, full-time in-state students at public four-year universities paid an average of about $1,920 in net tuition and fees in 2026 to 2027, after adjusting for inflation. At private nonprofit colleges, average net tuition and fees were about $17,280.
Why Sticker Price and Net Price Are So Different
About 70 percent of full-time undergraduates receive grant aid from colleges, states or the federal government. That is why a student financial planner compares schools by estimated net price. A private college with a high sticker price can sometimes cost less than a public university once institutional aid is applied.
How Does a Financial Planner Help Lower College Costs?
A financial planner helps lower college costs by improving how much aid a family qualifies for, steering the student toward schools likely to offer strong aid or merit scholarships, and making sure every form is filed correctly and on time. Small mistakes on the FAFSA or CSS Profile, such as reporting assets incorrectly, can reduce an aid package.
Planners typically help in five areas:
- Understanding aid formulas. How the FAFSA’s Student Aid Index and the CSS Profile used by some private colleges view your finances.
- Timing. Aid formulas use income from earlier tax years, so decisions before junior year can affect eligibility.
- A financially balanced list. Schools that fit academically and are likely to be affordable.
- Scholarships. Merit aid from colleges plus private local and national awards.
- Comparing offers. Separating free money from loans to find true out-of-pocket costs.
When Should Families Start Budgeting for College?
Families should start budgeting for college as early as possible, ideally when a student enters high school. By ninth or tenth grade, there is still time to adjust savings, understand how aid formulas will view the family’s finances and research schools by cost. Junior year is the latest practical starting point for aid strategy, because the FAFSA uses tax information from two years before college begins.
A rough timeline looks like this:
| Grade | Financial Planning Focus |
|---|---|
| 9th and 10th grade | Estimate future costs, review savings and 529 contributions, learn how aid works |
| 11th grade | Run net price calculators, build a financially balanced college list, research scholarships |
| 12th grade fall | File the FAFSA or CADAA and any required CSS Profile, apply for scholarships |
| 12th grade spring | Compare award letters, appeal aid if circumstances changed, choose a school and finalize the budget |
The 2027 to 2028 FAFSA opened in late September 2026, so seniors entering college next fall can file now. Federal Student Aid says most families can complete the redesigned form in about 15 minutes.
What Should California Families Know About Paying for College?
California families should know that state aid can significantly reduce college costs, but it depends on meeting deadlines. Students must submit the FAFSA or the California Dream Act Application and have a verified GPA on file by March 2, 2027 to be considered for a Cal Grant and the Middle Class Scholarship for the 2027 to 2028 school year.
The Cal Grant has income and asset limits that vary by family size, so it is worth checking eligibility each year rather than assuming you will not qualify. California’s community colleges also have the lowest average published tuition in the country at $1,440 a year in 2025 to 2026, according to the College Board, which makes starting at a community college and transferring a strong budgeting option for some students.
Is Hiring a Student Financial Planner Worth It?
Hiring a student financial planner is often worth it for families who expect to pay a significant share of college costs, have complex finances or feel unsure about aid forms. The value comes from avoiding costly mistakes, finding aid you might miss and choosing schools that fit your budget before the student falls in love with a school the family cannot afford.
| Family Situation | Recommendation |
|---|---|
| Simple finances and strong school counseling support | Free tools like net price calculators and FAFSA help may be enough |
| Business owners, multiple properties or complex income | Professional guidance on how aid formulas treat assets is especially valuable |
| Two or more children heading to college close together | A combined plan helps coordinate savings and aid across siblings |
| Student interested in private or out-of-state schools | Help comparing net prices and CSS Profile requirements adds clear value |
Before hiring anyone, ask what is included, how the advisor is paid and whether they also handle the admissions side. Planning admissions and finances together usually produces a better college list than treating them separately.
Why Choose College Planning Source for College Funding Help?
College Planning Source combines college admissions guidance with college funding planning, which lets families build a college list that is both ambitious and affordable. The San Diego firm was founded in 2005 by Michelle Mai, whose experience in the UC Santa Barbara financial aid office shaped the firm’s focus on helping families understand and plan for college costs.
In a 2017 Proactive Advisor Magazine profile, Mai described helping families with strategies that work within their budget, maximize cash flow and support tax savings, which is useful for parents who want college planned alongside retirement and other long-term goals.
For parents, the firm’s Essential College Funding program includes a personalized funding plan, guidance on financial aid and access to a private scholarship database. Students can also work with counselors through grade-specific admissions programs from ninth grade through senior year. Sessions take place over Zoom, and the office is located at 10875 Rancho Bernardo Road, Suite 115, in San Diego.
Families who want to learn the basics first can also join the firm’s free live webinars on admissions, financial aid and college funding.
Frequently Asked Questions
What is the difference between a student financial planner and a financial aid officer?
A financial aid officer works for a college and administers that school’s aid. A student financial planner works for your family across every school you are considering. The planner helps you estimate costs, prepare aid forms, find scholarships and compare offers, while the aid officer decides what one college will award and answers questions about that specific package.
Can a financial planner help if we make too much money for financial aid?
Yes. Many families assume they earn too much to qualify for help, but merit scholarships are awarded regardless of income, and some private colleges offer need-based aid to families with higher incomes than expected. A planner can also help higher-income families choose schools with strong merit aid, use tax-advantaged savings and plan cash flow so college does not derail retirement.
Should students take out loans to pay for college?
Loans can be a reasonable part of a college budget when they are limited and planned. A common guideline is to keep total student borrowing below the student’s expected first-year salary. Federal student loans generally offer more borrower protections than private loans, so families usually exhaust grants, scholarships, savings and federal options before considering private borrowing.
What happens during a free college planning assessment at College Planning Source?
The free assessment is a one-hour virtual meeting with a College Planning Source specialist. It can cover the student’s career and major interests, testing timelines, activities, deadlines, merit scholarships, a financially balanced college list and the family’s funding plan. Families leave with a clearer picture of expected costs and the next steps for both admissions and funding.
Build a College Budget That Works With College Planning Source
Paying for college is one of the biggest financial decisions most families make, and the best time to plan is before the acceptance letters arrive. A student financial planner helps you understand the real cost of each school, capture the aid and scholarships available to you and create a budget your family can sustain for four years.
College Planning Source has helped San Diego and Southern California families plan for both college admissions and college funding since 2005. Schedule your complimentary one-hour virtual college planning assessment to review your student’s goals, estimate costs at the schools on their list and map out a funding plan.
At College Planning Source, we help students and families navigate every step of the college admissions process. Get direct one-on-one guidance with a complimentary virtual college planning assessment—call 858-676-0700 or schedule online at collegeplanningsource.com/assessments.